The IRA Tax Bomb: $750K IRA Can Cost $200K in Taxes
You saved diligently into your 401(k) and traditional IRA for decades. You got the tax deduction every year. Now you have $750,000 — or maybe $1.5 million — sitting in pre-tax accounts, and it feels like a success story.
It is. But it is also a tax bomb with a fuse that starts burning at age 73 (or 75 if you were born in 1960 or later).
The Problem No One Warned You About

Run your own numbers — FREE
10,000 Monte Carlo simulations. Forward-looking forecasts from BlackRock, JPMorgan, Vanguard, GMO, Schwab, Invesco. No account needed.
Try QuantCalc Free →Every dollar in a traditional IRA or 401(k) has never been taxed. When you withdraw it — and eventually the IRS will force you to — it gets taxed as ordinary income. Not capital gains rates. Ordinary income rates: 22%, 24%, 32%, or higher depending on the total.
Required Minimum Distributions (RMDs) start at age 73 if you were born 1951–1959, and at age 75 if you were born in 1960 or later (26 CFR 1.401(a)(9)-2). The IRS sets how much you must withdraw each year from your balance and a life-expectancy factor (irs.gov — RMD FAQs, checked 2026-09-10). You cannot skip it. You cannot defer it. You pay the tax or you pay a 25% penalty on top of it.
Here is what makes this a bomb rather than just a bill: RMDs grow every year because they are a percentage of your remaining balance. If your IRA continues to grow (which it should, since you are invested), your forced withdrawals get larger. By your late 70s and early 80s, RMDs can push you into tax brackets you never occupied during your working years.
Run your own numbers in the free calculator →
The Math on a $750K IRA
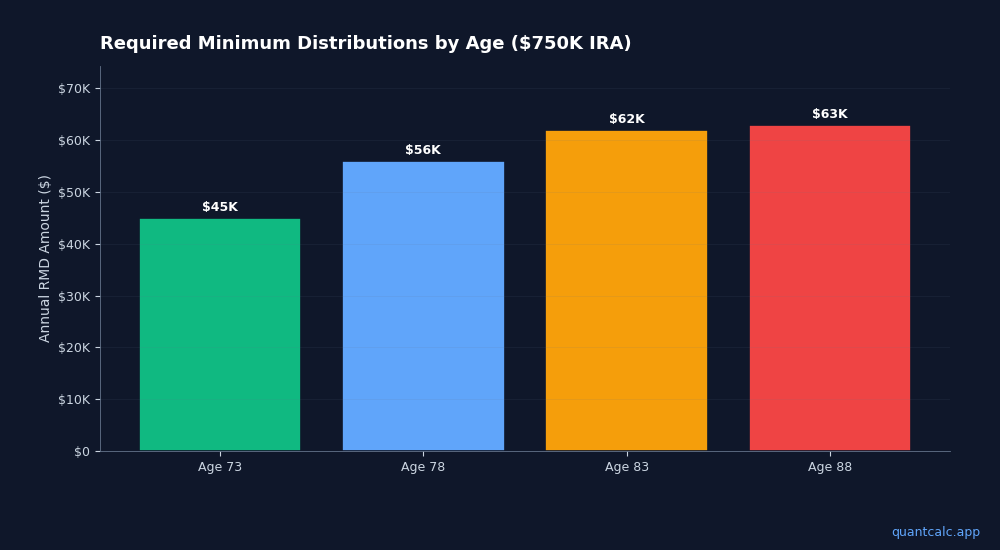
Assume a $750,000 traditional IRA at age 65 in 2026 (born 1961, so RMDs begin at 75), growing at 6% annually with no withdrawals until then. Each RMD is the balance divided by the Uniform Lifetime Table factor for that age:
- Age 75: Balance has grown to roughly $1,343,000. First RMD is approximately $54,600.
- Age 78: Balance is around $1,406,000. RMD is approximately $63,900.
- Age 83: Balance is around $1,459,000. RMD is approximately $82,400.
- Age 88: Balance is around $1,412,000. RMD is approximately $103,000.
Each of those withdrawals is just the prior year-end balance divided by that age's distribution period, so the 2026 RMD divisors are what turn a projected balance into a forced withdrawal — substitute your own numbers to see how large your first required year would be.
At 6% growth the balance keeps rising into your 80s even after the forced withdrawals start. Over a 20-year RMD period (ages 75–94), you withdraw roughly $1,780,000 in forced taxable income — and about $1.1 million is still in the account at the end. At an effective rate of 18-22%, that is roughly $320,000-$390,000 in federal taxes alone — on money you thought you were "saving" tax-free.
And that is just federal. State income taxes add another layer in most states.
Why This Hits Early Retirees Hardest
If you are 55 in 2026 (born 1971), your RMDs start at 75. Retire now and do not touch your traditional IRA until then, and you have 20 years of continued growth with zero withdrawals. That $750K becomes about $2.4M at 6% growth. Your first RMD at 75 is then roughly $97,800 — and it keeps rising from there.
The irony: the longer you leave it alone, the bigger the bomb gets.
Three Moves That Defuse It
1. Strategic Roth Conversions During Low-Income Years
The gap between early retirement and your RMD age (75 if you were born in 1960 or later) is the golden window. Your earned income is zero or minimal. You can convert traditional IRA money to Roth at historically low tax rates.
Under current OBBBA-permanent tax brackets (2026 figures from IRS Rev. Proc. 2025-32):
- A married couple with no other income can convert up to $133,000 and stay in the 12% bracket ($100,800 of taxable income after the $32,200 standard deduction)
- A single filer with no other income can convert up to $66,500 in the 12% bracket ($50,400 of taxable income after the $16,100 standard deduction)
If you convert $80,000 per year for 10 years from age 55 to 65, you move $800,000 out of the tax bomb and into a Roth where it grows tax-free forever. For a married couple with no other income, the federal tax cost is about $5,240 a year, roughly $52,400 in total (everything taxed at 10-12%) — compared to paying $200,000+ at 22-24% during RMDs.
2. Fill the Bracket, Not the Return
Do not convert so much that you push into an unnecessarily high bracket. The goal is to fill the 12% or 22% bracket each year — not to empty the IRA in one shot.
This is also where ACA subsidy planning intersects. If you are under 65 and on marketplace health insurance, Roth conversion income counts toward MAGI. Converting too much can push you over the 400% FPL cliff and cost you $8,000-$15,000 in lost subsidies. You need to optimize for both the tax bracket AND the ACA cliff simultaneously.
3. Plan Across the Full Timeline
The optimal conversion strategy is not "convert as much as possible." It is "convert the right amount each year, accounting for future RMDs, Social Security income, ACA subsidies, and IRMAA thresholds."
This requires modeling the interaction of:
- Current tax brackets vs. projected RMD tax brackets
- ACA subsidy cliffs (if under 65)
- IRMAA Medicare surcharges (if near 65)
- Social Security taxation thresholds (up to 85% of benefits can be taxed)
- State income tax brackets
Getting any one of these wrong can cost thousands per year.
Model Your Tax Bomb
The QuantCalc Monte Carlo Retirement Calculator lets you model multi-account withdrawal strategies across taxable, traditional IRA, and Roth accounts. You can see how different Roth conversion amounts affect your long-term tax exposure, ACA subsidy eligibility, and IRMAA brackets.
The ACA Cliff Calculator shows how much income room you have below the 400% FPL cliff at a given MAGI — the most you can convert that year without losing the subsidy. The ACA Bridge Optimizer sizes the conversion year by year.
For a detailed year-by-year withdrawal and conversion plan, the FIRE Tax Optimization Spreadsheet maps out the optimal sequence across all account types, tax brackets, and ACA/IRMAA thresholds.
The Bottom Line
A large traditional IRA is not a problem to have. It is a problem to ignore. The tax bill is coming whether you plan for it or not — the only question is whether you pay 12% now or 24% later.
The years between early retirement and your RMD age (73, or 75 if born in 1960 or later) are the best opportunity most people will ever have to restructure their tax exposure. Every year you wait, the bomb gets bigger and the window gets shorter.
Sources: 24/7 Wall St. — $750K IRA tax bomb, SDO CPA — Roth Conversion Strategies 2026, The College Investor — Roth Conversion Ladder